Many families are surprised to learn that, in some situations, life insurance can help cover the cost of home care. The answer depends on the type of life insurance policy you have and the options built into it. Understanding what’s available can make it easier to plan care without immediately relying on savings or making difficult financial decisions.
When I speak with families who are beginning to explore home care, one of the most common questions isn’t about care itself. It’s about how they’re going to pay for it. Home care can provide tremendous peace of mind, but families understandably want to know what financial resources they may already have.
One option that often gets overlooked is life insurance.
While not every policy can be used to pay for care, some policies offer benefits or features that may help fund in-home support while the policyholder is still living.
This guide explains when life insurance may help cover home care costs, what options are available in Canada, and what families should consider before making any decisions.
Can You Use Life Insurance to Pay for Home Care?
The short answer is: sometimes.
Traditional life insurance is designed to provide a death benefit to beneficiaries after the policyholder passes away. However, certain permanent life insurance policies may include features that allow policyholders to access part of their policy’s value during their lifetime.
Whether this is possible depends on several factors, including:
- The type of life insurance policy
- The policy’s cash value
- Available riders or living benefits
- The insurer’s terms and conditions
I’ve found that many families aren’t aware of these options because they purchased their policies decades ago and haven’t reviewed them since.
A conversation with the insurance provider or financial advisor can often clarify what’s available.
Which Types of Life Insurance May Help Cover Care?
Not all policies work the same way.
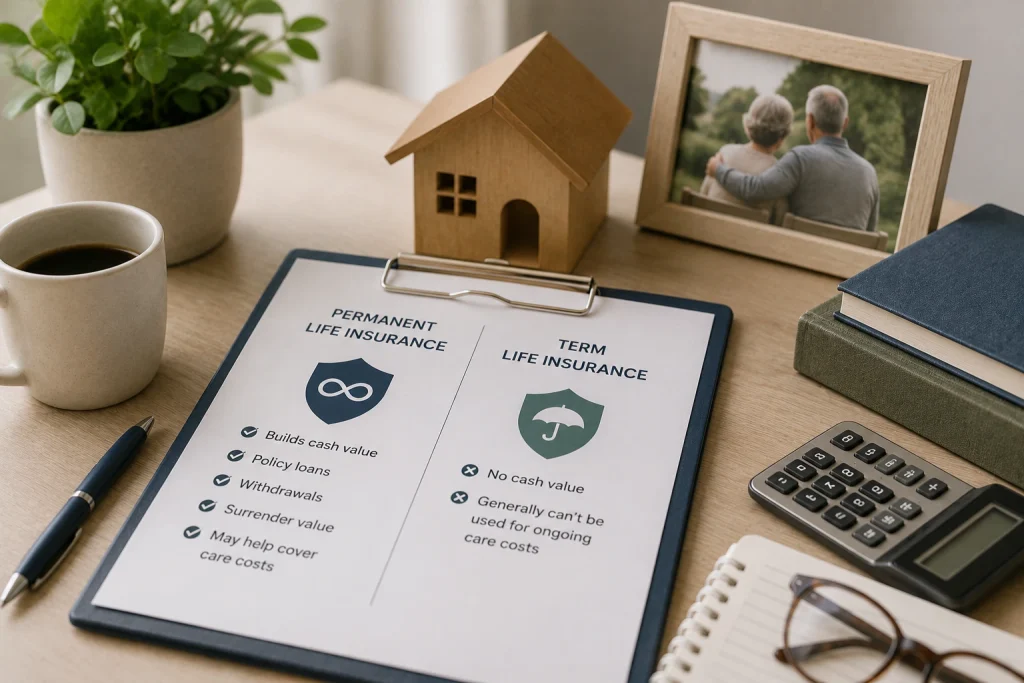
Permanent Life Insurance
Permanent life insurance, such as whole life or universal life insurance, may build cash value over time.
Depending on the policy, this cash value may be accessed by:
- Taking a policy loan
- Making a partial withdrawal
- Surrendering the policy
These funds can potentially be used for home care expenses.
One thing I’ve noticed is that many older adults purchased permanent policies years ago without realizing they had accumulated significant cash value.
Term Life Insurance
Most term life insurance policies do not build cash value.
Unless the policy includes specific living benefits or riders, it generally cannot be used to pay for ongoing home care.
What Are Living Benefits in Life Insurance?
Some life insurance policies include optional features known as living benefits.
These may allow access to policy funds while the insured person is still alive under certain circumstances, such as:
- Diagnosis of a terminal illness
- Critical illness
- Severe disability
- Long-term care needs (available in some policies)
Coverage varies significantly between insurers and policies.
Before making assumptions, it’s important to review the policy or speak directly with the insurance company.
Can You Borrow Against a Life Insurance Policy?
If a permanent policy has accumulated cash value, borrowing against it may be an option.
Families sometimes use these loans to help pay for:
- Personal care
- Companion care
- Overnight support
- Dementia care
- Respite care for family caregivers
I’ve seen this approach provide valuable flexibility for families who need care immediately while they explore longer-term financial planning.
It’s important to remember that policy loans typically accrue interest and may reduce the eventual death benefit if they aren’t repaid.
Can Home Care Help Delay More Expensive Care Options?
For many families, the goal isn’t simply finding a way to pay for care. It’s finding the most cost-effective way to help someone remain safely at home.
Many seniors only need assistance with a few daily tasks, such as:
- Meal preparation
- Bathing and dressing
- Medication reminders
- Light housekeeping
- Transportation to appointments
- Companionship
Starting with a few hours of support each week may help seniors maintain their independence while delaying or even avoiding a move to assisted living or long-term care.
In my experience, families often feel less overwhelmed when they realize care can be introduced gradually instead of all at once.
What Other Funding Options Can Help Pay for Home Care?
Life insurance is only one piece of the financial picture.
Families may also explore:
- Personal savings
- Pension income
- Government benefits
- Veterans’ programs (when eligible)
- Employer retirement benefits
- Family cost-sharing arrangements
- Tax credits for eligible medical expenses
Many families I speak with combine several funding sources rather than relying on just one.
A financial advisor can help determine the most appropriate strategy based on your individual circumstances.
Should You Access Your Life Insurance for Care?
There isn’t a one-size-fits-all answer.
Some important questions to consider include:
- Will accessing the policy reduce the benefit left for beneficiaries?
- Is home care expected to be temporary or ongoing?
- Are there other financial resources available?
- Would borrowing against the policy be preferable to surrendering it?
- Have you spoken with both your insurance advisor and financial planner?
I’ve found that families feel much more confident after reviewing these questions before making any permanent decisions.
When Should Families Start Planning for Care Costs?
One situation I commonly see is families waiting until after a medical emergency to think about finances.
Unfortunately, decisions often become more stressful when they’re made during a hospital discharge or following a sudden decline in health.
Planning ahead offers several advantages:
- More time to review insurance policies
- Better understanding of available benefits
- Greater flexibility in choosing care
- Less financial stress during a crisis
- More opportunity for seniors to participate in decisions
Even if home care isn’t needed today, reviewing available financial resources now can make future planning much easier.
Frequently Asked Questions About Life Insurance and Home Care
Can I use any life insurance policy to pay for home care?
No. Only certain policies, typically permanent life insurance with accumulated cash value or specific living benefit provisions, may offer this option.
Does using my life insurance reduce the death benefit?
It can. Loans, withdrawals, or surrendering part of the policy may reduce the amount ultimately paid to beneficiaries.
Should I speak with my insurance company before making decisions?
Yes. Every policy is different. Your insurer or financial advisor can explain the specific options available under your policy.
Is home care covered by provincial health insurance?
Some publicly funded home care services may be available for eligible individuals, but many families choose private home care to receive additional hours, greater flexibility, or specialized support.
Planning Ahead Can Make Care Decisions Easier
Exploring how to pay for home care can feel overwhelming, especially when a loved one has recently experienced a health change.
I’ve noticed that families often gain peace of mind simply by understanding all of their available options. Life insurance may be one of those options, but it’s rarely the only one. Taking the time to review your policy, speak with financial professionals, and understand the cost of care can help you make informed decisions that support both your loved one’s well-being and your family’s long-term financial goals.
The right funding strategy is the one that balances quality care with financial sustainability, allowing seniors to remain safe, comfortable, and independent for as long as possible.
Exploring Ways to Pay for Home Care?
Understanding your care options is an important part of financial planning. CareProvide can help you explore personalized home care services that fit your loved one’s needs and your family’s budget.